Ten minutes separates two entirely different claims in this city. Down near the old downtown, small houses from the twenties still carry original-era systems, shallow foundations and finishes that came out of an oil-boom construction economy. Up toward Carbon Canyon, hillside tracts from the nineties and 2000s sit on engineered pads with slope drainage and modern piping. The first produces plumbing failures inside aging walls. The second produces exterior water arriving all at once in a concentrated storm. Those two files get built differently from the first hour.
The canyon side is worth being blunt about. Brea's northern hills were shaped by the Brea Olinda oil field and later carved into building pads, and when a storm parks over that terrain the runoff can outrun what the slope drains were designed to carry. Whether any of that reaches coverage depends on where the water got in, which is why photographs come before cleanup. Down the hill, the retail district around Brea Mall and the surrounding commercial corridor bring a steady share of tenant-improvement losses, where the lease decides which carrier owns which part.
What Brea Changes About Insurance Claim Help
1Concentrated canyon storms and the storm date
Carbon Canyon runoff arrives in bursts, and the difference between a covered sudden event and an excluded ongoing condition often comes down to timing. We record the date and hour of discovery, attach the storm to it, and photograph the drainage path while it's still wet. A file assembled three days later, after the sun and a landscaper have been through, is a much weaker file.
2Downtown-era homes hide their assemblies
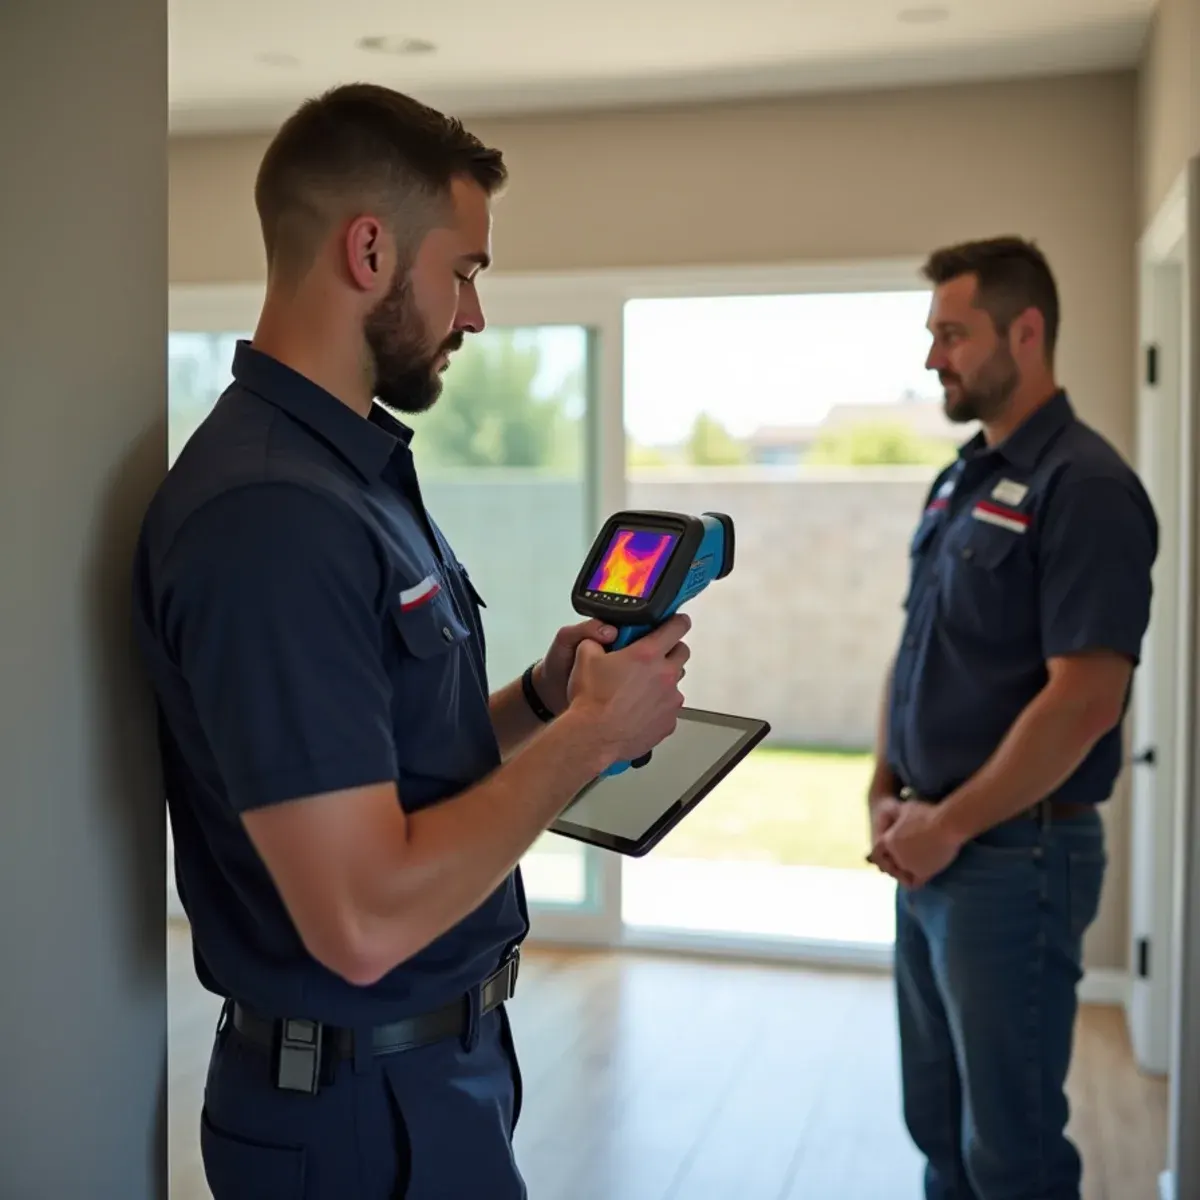
The small houses near old downtown Brea hold surprises: layered flooring, added rooms with nothing in the permit record, plumbing spliced through three generations. All of that affects scope and all of it gets questioned if it appears in an estimate without explanation. We photograph what's behind the wall as we open it, so extra line items arrive with evidence attached rather than after a denial.
3Retail tenancy at Brea Mall and the corridor
For commercial tenants here, the lease usually splits responsibility between building shell and tenant improvements, and the two are insured by different parties. We scope them separately from the start and document inventory and fixtures on their own. Blended estimates in leased retail space are the most common reason a Brea commercial file sits unapproved.
How the Work Runs
The method is the same one we use on every insurance claim help job, documented to the IICRC S500:2025 standard. Here it is in short — the full water damage insurance claim assistance process explains each stage in detail.
- Photograph before anything moves
- Map moisture and set the category
- Open the file with the right facts
- Write the scope in their platform
- Daily drying logs and supplements
- Completion documents that release depreciation
The Brea Background Worth Knowing
Brea's hillside tracts were designed to handle rain. Terrace drains catch runoff partway up a slope, v-ditches carry it around the toe, area drains take the flat yard, and everything ties into a system that moves water past the house rather than through it. The design works. What fails is maintenance. Over a dry summer those inlets fill with eucalyptus leaf litter, decomposed granite, and whatever the wind brought down the canyon, and nobody looks at them because they sit on a slope behind a fence. The first hard storm of the season finds every one that is blocked.
There is more on the housing stock, drainage and plumbing history of this city on our water damage restoration in Brea page.
Brea at a glance
- Dominant construction era
- 1920–2005
- Foundation type
- mixed on grade
- Supply piping found here
- galvanized steel, under-slab copper, PEX in newer hillside tracts
- Drain line materials
- cast iron, clay, ABS
- Terrain and water table
- hillside-mixed, deep water table
- Most common local failure
- canyon and hillside runoff overwhelming slope drainage during concentrated storms
- Highest-value local prevention
- keeping Carbon Canyon-side slope drains, v-ditches and downspout extensions genuinely clear
What It Costs in Brea
We do not quote a number over the phone before seeing the property — anyone who does is guessing. The variables that actually move the price on a insurance claim help job are how quickly the loss was documented, category and class of water, whether the materials still match, and they are broken down in full on the water damage insurance claim assistance page. The assessment and the written estimate are free anywhere in Brea, day or night, with no obligation.
Insurance Claim Help Questions from Brea Homeowners
Photograph everything while it's still wet, including outside — the drain inlets, the flow path down the slope, where the water crossed the threshold. Note the time you found it. Don't clear the drains yet if you can safely wait. Then call your carrier and describe what you saw without labeling it. We'll handle the moisture mapping and the itemized scope. Coverage on storm runoff is your insurer's determination, and the photographs are what it gets made against.
No, and the distinction matters. A public adjuster is licensed to represent you in negotiating your settlement and charges a percentage of it. We are a restoration contractor. We document the loss, write and defend the scope of the physical work, and bill your carrier directly for it. If your claim turns into a genuine coverage dispute rather than a scope disagreement, that is the point to consider a public adjuster or an attorney, and we will say so.
Sometimes no. If the total loss is close to or below your deductible, filing puts a claim on your record without producing a payment worth having, and claim history affects renewal in California's current market. Get a written estimate first and compare it to your deductible before you call your carrier. We will give you that number without a claim being open. Any company that pushes you to file before you have seen an estimate has told you something.
Usually not under a standard homeowners policy. Water that runs across the ground and enters a building is surface water, and that is an excluded cause on nearly every form, whether it came off a Carbon Canyon slope or out of the street. Separate flood coverage handles it. Damage from a covered failure is a different story, so let us document the entry point and cause before anything gets cleaned up.