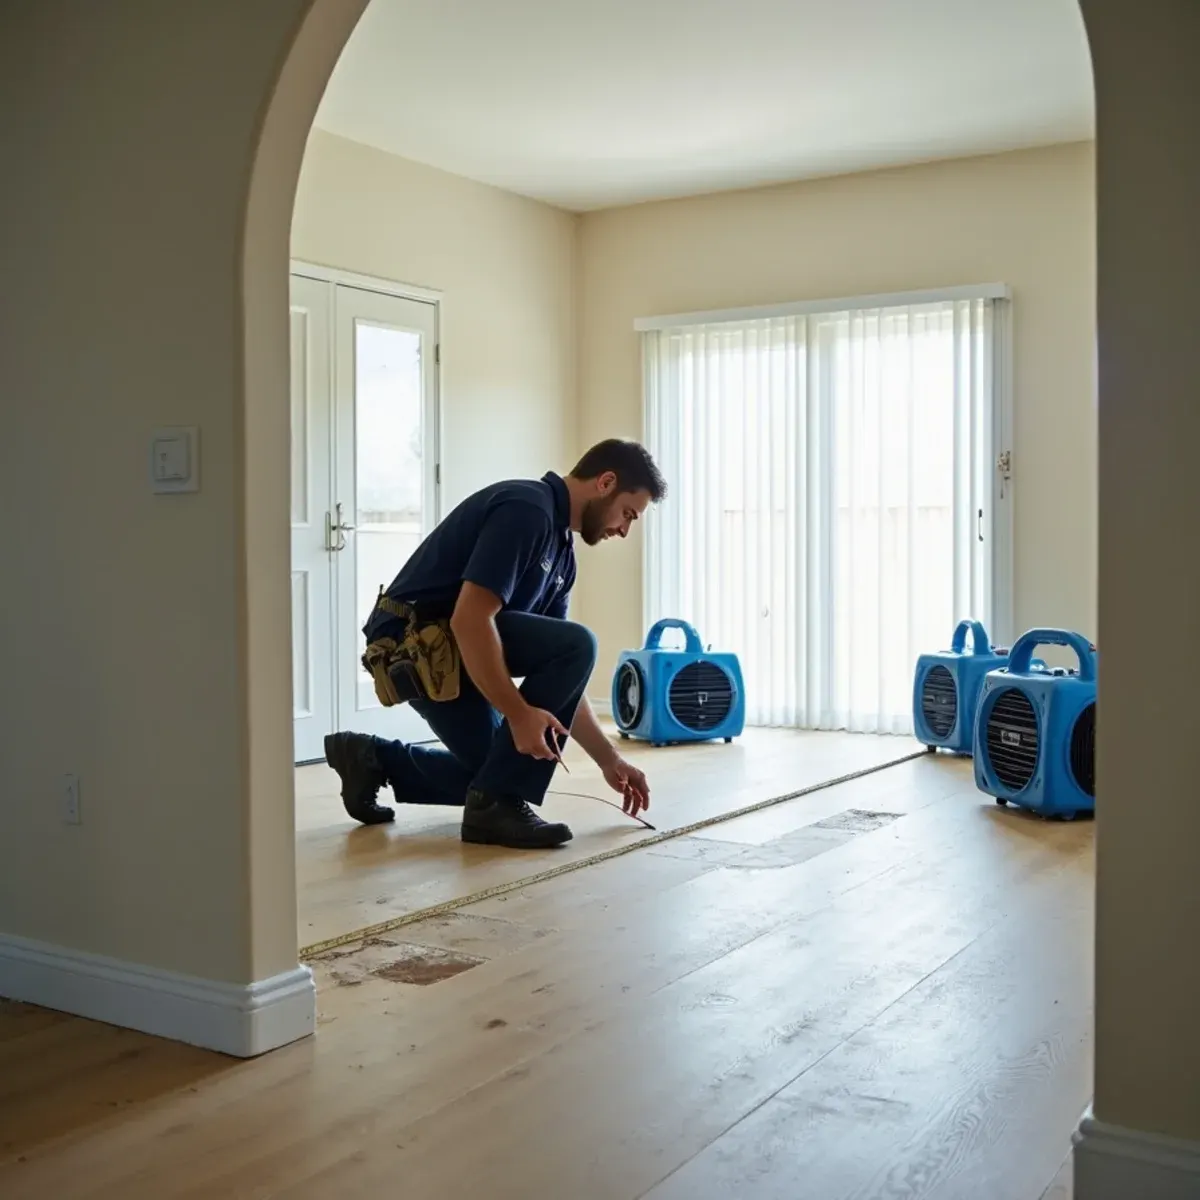
Ask three restoration companies what a water loss costs and you will get three non-answers, and there is a legitimate reason for it: the same visible puddle can be a two-day dry-out or a six-week reconstruction depending on things nobody can assess over the phone.
That said, refusing to discuss cost at all is unhelpful and it lets bad actors operate. So here is how the pricing genuinely works, what drives it up and down, and what to look for in an estimate — without inventing numbers we cannot stand behind for your specific property.
One structural point before anything else: restoration is billed in two separate phases with separate pricing logic. Confusing them is where most of the sticker shock comes from.
Phase 1 vs. Phase 2: Mitigation and Reconstruction Are Different Bills
Mitigation is the emergency phase — extraction, removal of unsalvageable material, and structural drying. It is priced from standardized industry schedules that insurance carriers use, largely by affected square footage, equipment count, and days on site.
Reconstruction is putting the building back — drywall, texture, paint, flooring, cabinetry, trim. It is priced like any construction project, by materials and labor.
On most water losses, reconstruction is the larger of the two, often substantially. A homeowner who has only been quoted for mitigation and assumes that is the whole number is going to be unpleasantly surprised, which is why we write the reconstruction estimate while drying is still running rather than after.
What Actually Drives the Mitigation Number
Five things account for the great majority of the variation between one job and another:
- Water category. Category 3 work costs several times an equivalent Category 1 loss because of containment, PPE, disposal, and disinfection requirements.
- Affected square footage. Priced on the drying chamber, not the puddle — water that wicked into four rooms is a four-room job even if it was only visible in the hall.
- Equipment days. Billed per unit per day, so a three-day dry-out and a nine-day dry-out on the same footprint differ by a factor of three on that line.
- Material removal and disposal. Carpet pad, wet insulation, drywall cuts, and cabinet toe-kick removal each carry labor and dump fees.
- Access and timing. After-hours emergency mobilization carries a call-out rate, and difficult access (second floor, long hose runs, tight lots) adds hours.
What Drives the Reconstruction Number
Reconstruction is more familiar territory for most homeowners because it follows remodel logic.
The dominant factor is simply how much came out during mitigation, which is why drying in place matters financially and not just as a convenience. Beyond that: finish level and material availability (a discontinued flooring product can force a larger replacement area than the damage), texture matching difficulty, whether permits and inspections are triggered, and whether code upgrades come into play when a wall is opened.
That last one is worth knowing about. Opening a wall sometimes obligates you to bring electrical, insulation, or egress to current code. Many policies include ordinance-and-law coverage specifically for this, and identifying it early is what gets it into the claim rather than onto your credit card.
How to Read an Estimate and Spot a Bad One
A legitimate mitigation estimate is itemized and measurable. It should show affected square footage by room, the equipment type and count with days, material removal by unit, and the water category. You should be able to walk the house with the estimate and verify each line.
Warning signs, in rough order of how much they should concern you:
- A lump-sum number with no line items. There is no way to verify anything and no way to compare bids.
- Pressure to sign immediately during the emergency. Legitimate companies will start mitigation and finalize paperwork after — the urgency is about the water, not the contract.
- A signed authorization that assigns your insurance benefits without that being clearly explained. Read what you sign, even at 2 a.m.
- No moisture readings offered. If nobody is measuring, nobody knows when drying is done — including them.
- A quote given over the phone before anyone has seen the property. It is a guess, and it will change.
- Refusal to provide a license number or certification on request.
What Insurance Typically Pays and What It Does Not
The general shape, with the caveat that policies vary and yours is the one that matters:
Usually covered: sudden and accidental water damage from an internal source — a burst pipe, a failed appliance supply line, a water heater rupture, a fire suppression discharge. Both the mitigation and the reconstruction are covered, along with additional living expenses if the home becomes uninhabitable.
Usually not covered: the failed component itself (the pipe, the water heater, the appliance), gradual leaks and long-term seepage, damage attributed to deferred maintenance, ground-source flooding without separate flood insurance, and sewer backup without a specific water backup endorsement. Mold is typically covered only when it results directly from a covered sudden loss, and often capped at $5,000 or $10,000.
Where Homeowners Lose Money on a Claim
Four recurring mistakes, all avoidable:
Not documenting before cleanup. Photographs taken before anything moves are the strongest evidence in the file, and they cannot be recreated later.
Waiting to start mitigation. Beyond the additional damage, a carrier can decline the portion of a claim attributable to a failure to mitigate. Delay costs twice.
Accepting the first scope without question. Initial estimates frequently cover only the visibly damaged section and miss the blending question — why a partial flooring or texture repair will not match. That argument has to be made with documentation.
Not claiming recoverable depreciation. Replacement-cost policies hold back depreciation until the work is complete and then release it on proof. A meaningful number of homeowners never submit that documentation and simply leave the money.
When It Is Not Worth Filing
Sometimes the honest answer is not to file, and we will tell you when we think that is the case.
If the total loss is close to or below your deductible, filing accomplishes nothing except putting a claim on your record — and in California's current homeowners insurance market, claim history genuinely affects renewal and pricing. A small clean-water loss confined to one room with no material removal frequently falls into this category.
The way to decide is to get a written estimate first and compare it to your deductible before you call your carrier. Any restoration company should be willing to give you that number without a claim being open, and if they push you to file before you have seen the estimate, that tells you something.
Why Two Similar-Looking Jobs Price Differently
From our crews in the field
Square footage is the number people expect to drive the price, and it is one of the weaker predictors. What actually drives it is the number of affected materials and their density. A 200 square-foot room with saturated hardwood over a slab costs more to dry than a 500 square-foot room of tile and painted drywall, because the hardwood needs mat systems, more equipment days and daily monitoring.
The second driver is category. Contaminated water brings containment, PPE, HEPA filtration and disposal of porous material — a different job with a different labour profile, not the same job with a surcharge.
The honest part: be sceptical of anyone who quotes a firm total over the phone before reading moisture. They are either guessing, in which case the number will change, or pricing high enough to cover the worst case. What you should get on the phone is a range and an explanation of what would move you within it.
- Material density and category drive cost more than floor area
- Equipment days are the largest single line on most drying invoices
- A firm total quoted before a moisture inspection is a guess or a cushion
- On a covered claim your real number is usually the deductible
Services Mentioned in This Guide
- Emergency Water Damage Restoration in Cypress, CA — A live person answers in three rings and a truck rolls in 30 minutes — any hour, any day, anywhere in Cypress.
- Water Damage Repair & Reconstruction in Cypress, CA — The same team that dried it puts it back — drywall, texture match, flooring, cabinetry and paint, under one contract.
- Structural Drying & Dehumidification in Cypress, CA — LGR dehumidifiers, calculated air-mover placement, and a daily moisture log that proves the structure actually dried.
- Water Damage Restoration in Cypress, CA — Predominantly single-story slab-on-grade tract homes built between 1960 and 1980, with a newer band of construction from the 1990s onward on the west side.
- Water Damage Restoration in Buena Park, CA — A larger, more varied city than its neighbors, with 1950s and 1960s tracts, later infill, extensive multi-family housing, and a substantial hospitality and retail corridor.
Frequently Asked Questions
Because the answer depends on things that cannot be assessed remotely — how far the water traveled inside the assemblies, what the moisture readings actually are, and what category the water is. Anyone who quotes a firm number sight unseen is either guessing or planning to revise it once they arrive.
On a covered claim we bill the carrier directly and you are generally responsible only for your deductible. If you are paying out of pocket, we provide a written estimate before starting and you approve the scope.
Yes, 24 hours a day, with no obligation. That includes the moisture inspection and a written estimate. You are free to get other bids, and we would rather you did than felt cornered.
It can, and in California's current market claim history is being weighted more heavily than it used to be at renewal. That is exactly why we recommend getting a written estimate and comparing it to your deductible before opening a claim on a small loss.
Get the Number in Writing, Then Decide
The single most useful thing you can do is get a written, itemized estimate before making any decision — about hiring, about filing, about anything. It costs nothing, it takes half an hour, and it converts a stressful unknown into a number you can evaluate.
We give that estimate free anywhere in Cypress and the surrounding cities, and we will tell you honestly when we think the loss is small enough that filing a claim is not in your interest.
Open 24 hours a day, 7 days a week — including holidays
On-site within 60 minutes of your confirmed emergency call anywhere in Cypress — or we credit $100 off your final invoice.